Compound interest, explained without the jargon
Interest can earn interest when it stays in an account, but the result depends on time, rates, compounding frequency and costs.
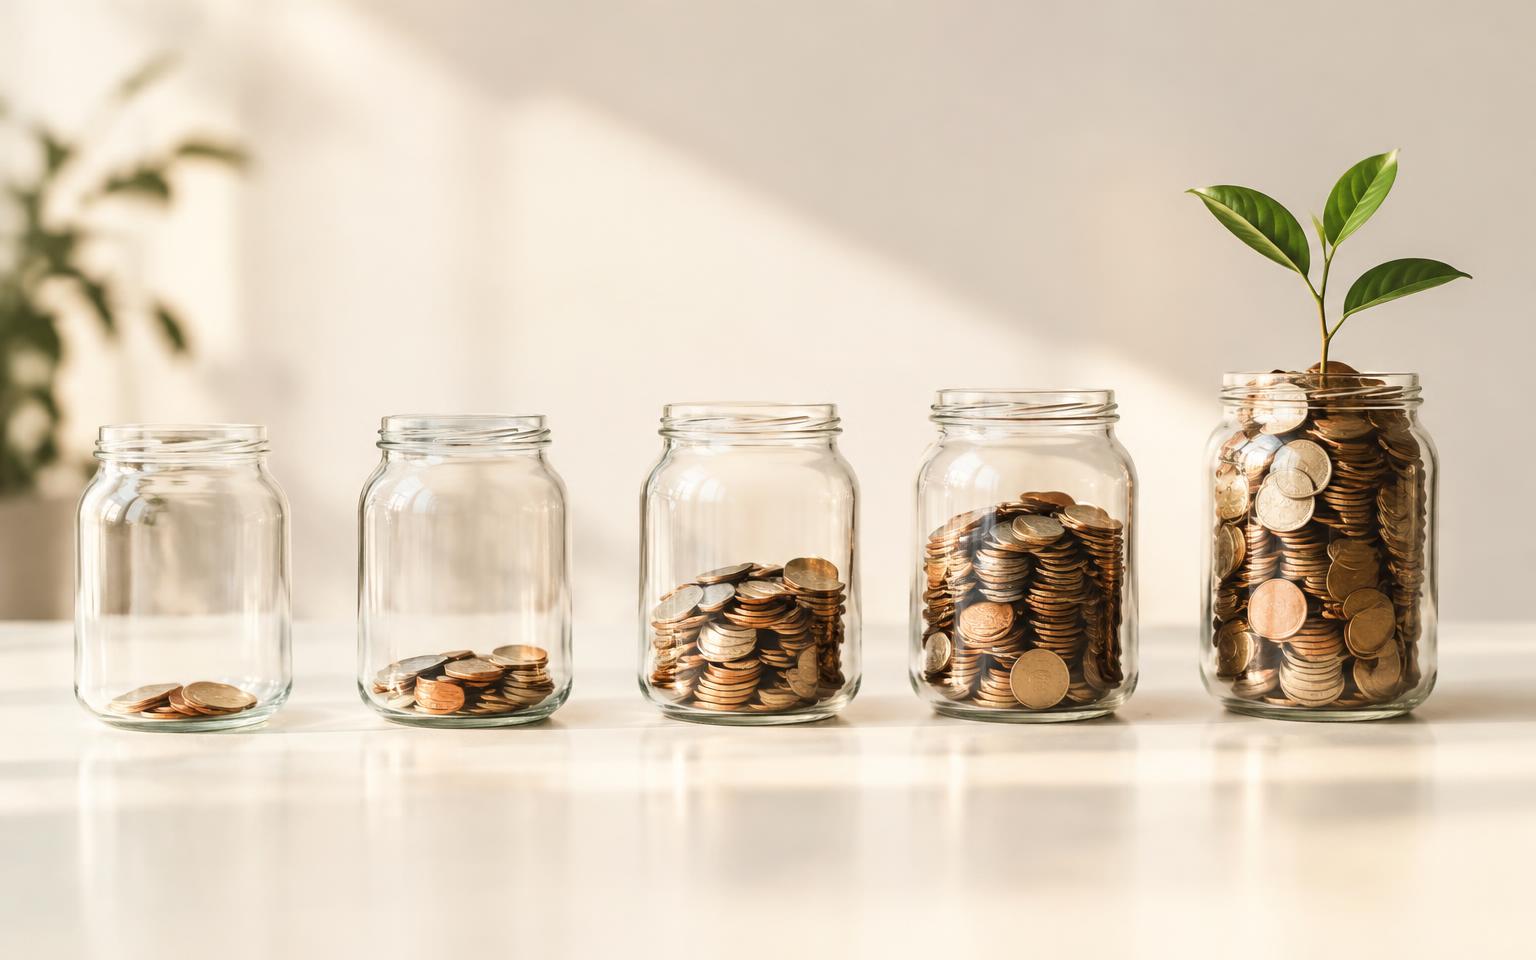
Compound interest means earning interest on both your original money and interest already added to it. The arithmetic is straightforward. The important part is understanding the assumptions behind any growth projection.
A clearly hypothetical example
Suppose you deposit $1,000, earn a fixed 5% a year compounded annually, and leave all interest in the account. Assume no further deposits, withdrawals, fees or taxes.
- After one year, you have $1,050: $50 in interest.
- After two years, you have $1,102.50: the second year earns $52.50.
- After ten years, you have about $1,629.
- After thirty years, you have about $4,322.
The calculation multiplies $1,000 by 1.05 once for each year. The rate stays the same, but each year’s interest is calculated on a larger balance. Investor.gov explains the same principle in its compound-interest lesson.
These figures illustrate a fixed-rate assumption, not a forecast. If the rate changes or money leaves the account, the result changes too.
The rule of 72
To estimate how many years money takes to double, divide 72 by the annual percentage rate of growth. At 5%, that gives about 14.4 years. At 8%, it gives about nine years.
This is a shortcut, not an exact calculation or a promise. It assumes a steady positive rate and money left to compound. It does not make an uncertain investment return predictable.
Frequency matters, but compare like with like
Holding the quoted nominal annual rate constant, more frequent compounding produces a higher effective annual yield. A hypothetical 5% nominal annual rate compounded monthly produces about 5.12% over one year, because each month’s rate is 5% divided by 12.
A deposit account’s annual percentage yield, or APY, reflects compounding. Do not assume that an advertised 5% APY will become 5.12% merely because interest compounds monthly: the compounding is already included in APY. Check the account disclosures and whether the rate can change.
Time helps, but contributions matter too
With a positive fixed rate and no withdrawals, the dollar amount of interest grows over time. Starting earlier gives a deposit more opportunities to compound.
That does not mean a smaller early deposit always beats larger later deposits. The outcome depends on how much is saved, when it is added and the return earned. Compare those inputs rather than relying on an early-start slogan.
Debt can compound too
Some credit cards calculate interest daily and add it to the balance, so interest itself can begin earning interest for the lender. The CFPB explains this in its daily-periodic-rate guidance.
Methods and terms vary, so read the agreement. Reducing a balance on which interest is charged reduces the amount exposed to future interest; new purchases or fees can offset that progress.
Costs and purchasing power
Money deducted in fees is no longer available to earn future returns. In a hypothetical comparison, $1,000 growing at a net 5% for thirty years becomes about $4,322; at a net 4%, it becomes about $3,243. That illustrates a one-percentage-point annual drag, not the fee structure of a particular product.
A larger balance also need not buy more. If both your balance and prices rise by exactly 3% over a year, purchasing power is unchanged before fees and taxes. Check the assumptions, costs and inflation—not just the impressive-looking final balance.
This explainer is general education, not financial advice.
Sources and further reading
Newsletter
The Daily Blend, in your inbox
Related stories
Why Futures Traders Use Market Replay: A Look at NQBacktest
A look at browser-based futures practice across Nasdaq, S&P 500 and gold, with a repeatable replay workflow and clear simulation limits.
Estée Lauder raises annual outlook after stronger September quarter
The beauty group lifted fiscal 2027 sales and adjusted-profit forecasts while reporting 7% quarterly net-sales growth.
OPEC+ keeps December targets steady, with next review on November 29
Seven producers retain September production requirements for December; output targets remain distinct from barrels actually reaching buyers.